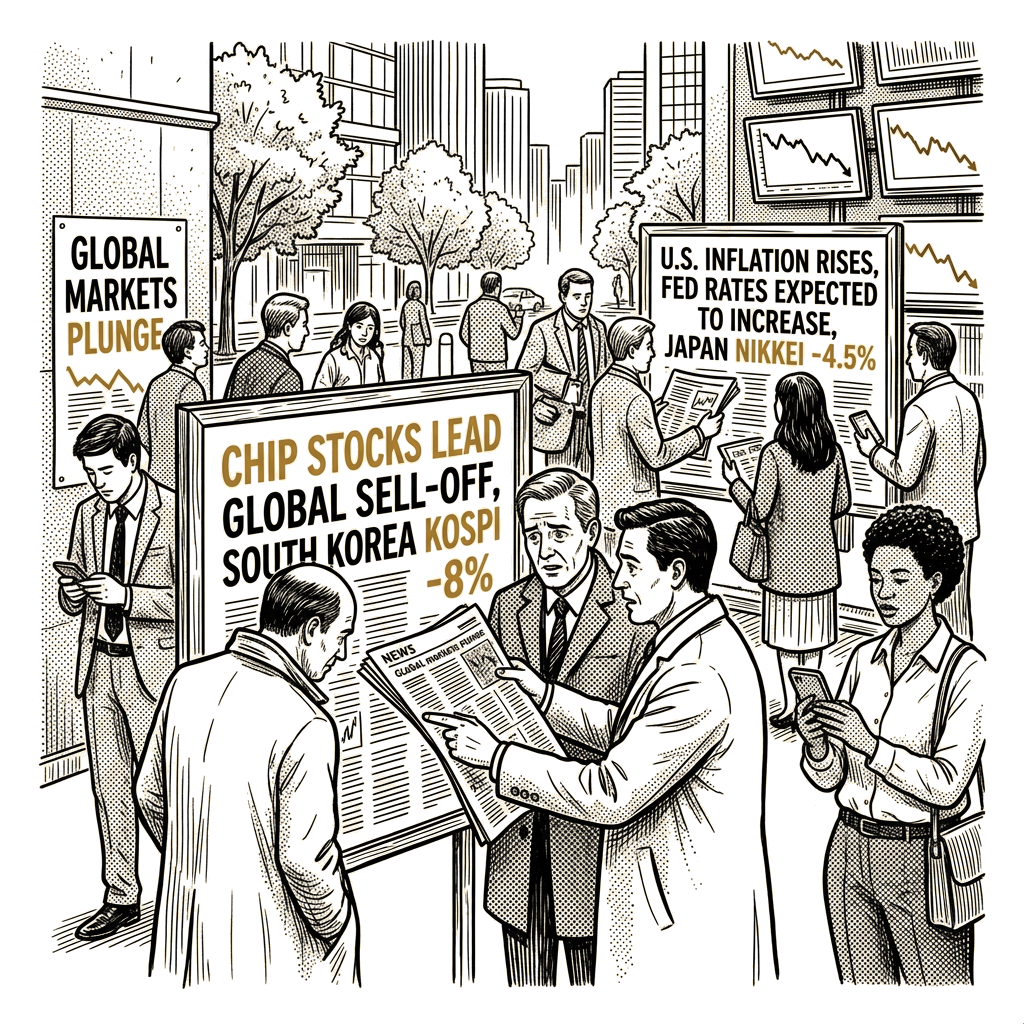
Four indexes and one price series carried Thursday’s session. South Korea’s KOSPI fell more than 8 percent; Japan’s Nikkei 225 fell 4.5 percent in late trading. Samsung Electronics fell 9 percent and SK Hynix fell 10.5 percent. Those declines extended Wednesday’s US session, where the S&P 500 lost 1.1 percent, the Nasdaq Composite lost 1.9 percent, and Dell lost 11 percent in a day.
The proximate cause is not in Seoul. It is the consumer price index for September, released Wednesday and read through FRED: the prices urban consumers actually paid rose 3.7 percent against a year earlier. That reading arrived after the sharpest sequence of policy increases since 1981 — four consecutive 75-basis-point steps in 2022 — and it moved in the direction the committee has spent three years trying to prevent it from moving.
Two points of convention before the commentary arrives.
First, 3.7 percent is not the number the Federal Reserve targets. The committee’s 2 percent objective is stated in terms of the personal consumption expenditures price index, not the consumer price index. The two are constructed differently: the PCE covers a broader basket and reweights it as spending shifts, which normally leaves it running below the CPI on the same month’s data. The market watches the CPI because it arrives first and because it prices the grocery basket and the rent. It is a proxy, and on Wednesday it was a proxy pointing the wrong way.
Second, composition matters more than the level. Chris Weston, an analyst at the brokerage Pepperstone, put it in the language the desk uses: “Further evidence of right-tail inflation risk in the US has reinforced the higher-for-longer rates narrative, with sellers emerging across risk assets and interest rate-sensitive equities coming under renewed pressure,” he said, quoted in the Guardian’s live coverage. “The breadth of price pressures across the CPI basket has been particularly concerning, challenging a market desperately in need of evidence of disinflation.” A headline driven by one volatile component can be set aside at the next release. A broadening basket cannot, and the Federal Open Market Committee reads the composition table before it reads the headline.
That is why the chip names moved furthest. Semiconductor and AI-linked equities carry the longest cash-flow duration in the index — most of their value sits in revenue expected years out, and the present value of a distant dollar falls arithmetically as the risk-free rate rises. When the September print raised expectations for the policy rate, the discount rate applied to those distant cash flows rose with it, and the names carrying the most duration fell furthest. Dell’s 11 percent decline is the same mechanism with a second question attached: Dell sells hardware into enterprise capital budgets, and a hardware vendor losing a ninth of its value in a session is the market marking down the assumption that enterprise spending on artificial intelligence will arrive at the scale and pace already capitalized into the foundry and memory names.
We have tracked this unwind through the summer — the KOSPI’s 10.5 percent July decline, the August follow-through in the same index, and the September leg that ran from the bond market. Each episode was described at the time as an entry point. The cumulative move is now the finding.
The repricing is not, however, confined to shareholders. It has three other sets of books, and all three are larger.
Begin with households. The 30-year fixed mortgage rate tracks the ten-year Treasury yield, which embeds expected future policy rates; a credible higher-for-longer path lifts the long end, and the mortgage rate lifts with it. Households that locked 30-year mortgages near 3 percent in 2021 cannot refinance into today’s market, and the same arithmetic discourages them from selling — a lock-in effect that has held existing-home inventory below its pre-2020 norm and left first-time buyers facing an asking price set by a market with nothing in it. Adjustable-rate mortgages reprice off short-term benchmarks that move with the funds rate. Credit-card annual percentage rates are conventionally priced off the prime rate, which is the funds-rate target plus 300 basis points. None of these instruments renegotiate on the committee’s calendar. They reprice on the household’s.
There is also a channel that appears in no market commentary. The cost-of-living adjustment for Social Security is calculated from the consumer price index for urban wage earners and clerical workers — a third index — averaged over July, August and September, and announced in the middle of October, which is to say this week. Section 215(i) of the Social Security Act fixes the formula. The September print is one of its three inputs. The same inflation reading that raises the odds of a rate increase also sets next year’s benefit check, and that check then meets a Medicare premium and a prescription price adjusted on the same twelve-month arithmetic. The committee’s objective and a retiree’s income are calibrated to one number from opposite directions.
Then workers. Samsung and SK Hynix are not merely the two largest listings on the KOSPI. They anchor an employment and supplier cluster on which Korean industrial policy has been built for three decades, and their capital plans set the order book for the firms beneath them. The exposure is not only foreign. The CHIPS and Science Act (Public Law 117-169, August 9, 2022) committed $39 billion in manufacturing incentives for domestic semiconductor facilities, and the same statute created a 25 percent advanced manufacturing investment credit, codified at Internal Revenue Code section 48D, for qualified facilities and production equipment. The taxpayer is already a party to this capital-expenditure cycle whether or not the equity market is. When demand assumptions for AI hardware are marked down, the utilization assumptions behind those fab plans are marked down with them. The public commitment is not marked down at all.
And the government’s own ledger. A higher policy rate is also a higher refinancing cost: maturing Treasury debt rolls over at the prevailing rate, so the average interest the Treasury pays on the outstanding stock rises as cheap, old debt is replaced. The Congressional Budget Office’s long-term budget outlook has carried net interest among the fastest-growing categories in the federal budget, and the arithmetic in that report turns on precisely one variable the committee is about to set.
What the committee can actually do at the end-of-month meeting is worth stating exactly, because the coverage does not. The Federal Open Market Committee sets the target range for the federal funds rate: seven governors plus five of the twelve Reserve Bank presidents — including the president of the Federal Reserve Bank of New York, who votes every year — on the statutory rotation. Its statutory objective is the dual mandate in section 2A of the Federal Reserve Act, maximum employment and stable prices, as elaborated in the committee’s Statement on Longer-Run Goals and Monetary Policy Strategy, most recently revised on August 22, 2025, which replaced the flexible-average-inflation-targeting construct with flexible inflation targeting and restored symmetric treatment of employment shortfalls in place of the 2020 “shortfalls” formulation. Under that framework the committee has three options. It can hold the target range and revise the risk language in the post-meeting statement — the least costly option, and the one the market currently expects. It can raise the range, which would reverse the direction prices have been assuming for most of the year and would record, in the statement’s own language, that the committee judged its existing setting insufficient. It can cut, which is not available at 3.7 percent against a 2 percent objective in the absence of a labor-market discontinuity that Thursday’s initial jobless claims — released at the same hour as the September producer price index — do not currently show. Note the calendar: the end-of-October meeting is not one of the four projection meetings, so there will be no summary of economic projections. The market gets the statement on the day and the minutes three weeks later. Whatever the committee decides, the record of it will be one document, and the incidence of it will fall across balance sheets that appear nowhere in it.
The IMF and World Bank Annual Meetings in Bangkok are absorbing the same figure. A higher US policy path strengthens the dollar against the financing currencies of emerging-market sovereigns with dollar-denominated debt and pulls capital toward dollar assets; the Fund’s external-balance assessments, published at these Meetings, are written against that constraint. The United Kingdom’s August gross domestic product figures, released Thursday morning and expected to show a 0.1 percent contraction after a strong July, are the same pressure arriving from the other side: rate-sensitive economies with no room to ease while their own inflation work is unfinished.
Two distinct things are being repriced in these numbers, and they should not be run together. The first is mechanical: at a higher risk-free rate, a fixed stream of distant cash flow is worth less, and no amount of narrative alters that arithmetic. The second is empirical: whether enterprise capital spending on artificial intelligence earns its cost of capital at the scale already capitalized into the equipment and memory names. The September CPI settles the first question. It does not settle the second; that one will be answered in capital-spending surveys and in the quarterly reports, unevenly, over the next year.
What is not in doubt is where the decision lands first. The committee’s rate path reaches the household repricing an adjustable mortgage, the retiree whose benefit check was computed from three months of price data, and the fab payroll funded in part by a tax credit the Treasury cannot withdraw — before it reaches the shareholder.
The committee meets at the end of the month, days before the first Tuesday in November. Its statement will run two pages. Its consequences will not.