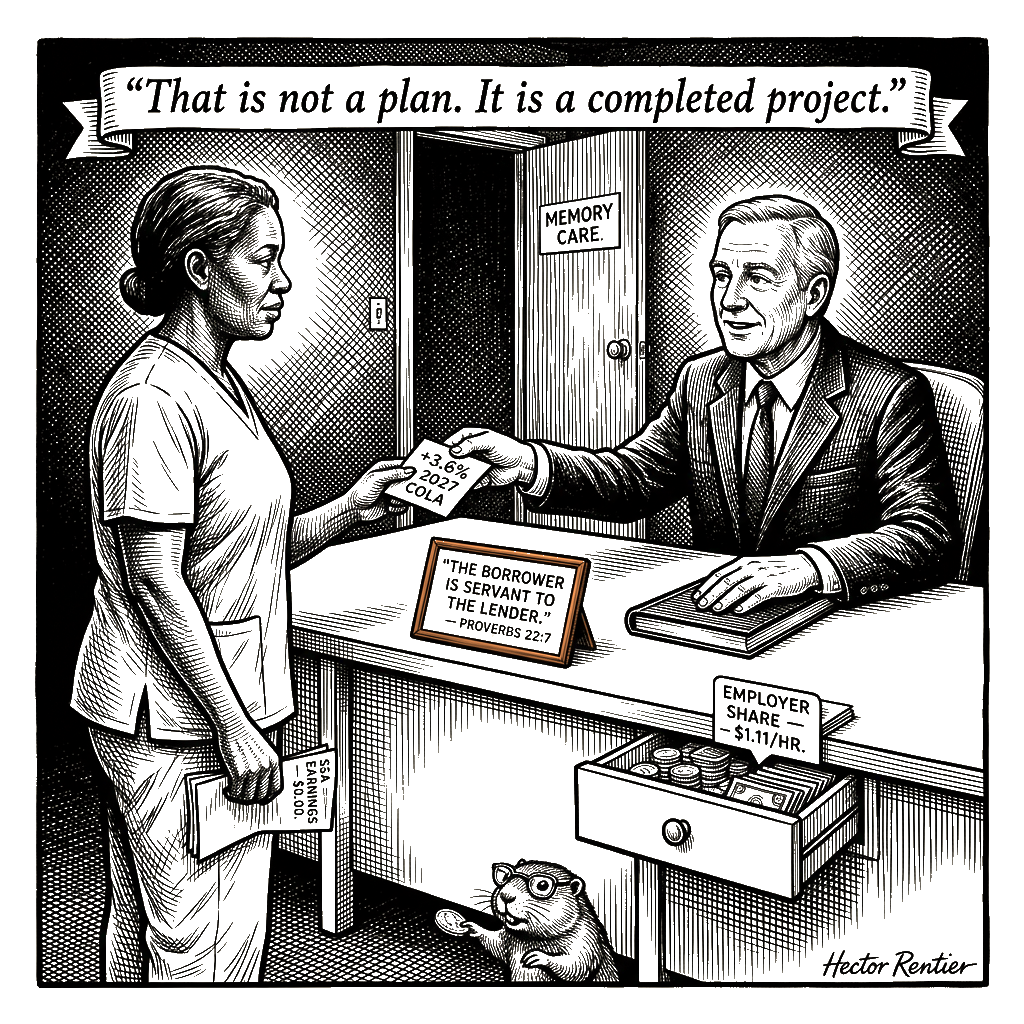
Darlene is a certified nursing assistant on the memory-care floor at the 96-bed building I own outside Zanesville, Ohio. She is 58. I bill the Medicaid desk $24.10 an hour for her labor and I pay her $17.85. The $6.25 between those two numbers is my evenings. Her back is a thing I have never asked about. The call light your mother will press in 2039 lands on her assignment sheet. I have paid her every Friday for 11 years and I have not reported one hour of it to the Social Security Administration.
God keep the schedule.
The payroll tax is 12.4% of her wage. Half of it — $1.11 an hour — is the employer’s share. I owe it. I keep it. That $1.11 is not mine. It never was mine. It is the first half of her pension and I have been keeping it in my drawer since 2015.
The second half does not exist. She is a 1099. The second 6.2% is not withheld from her check, not matched by me, not remitted, and no account is opened in her name at the Social Security Administration.
Here is the principle the case was only an example of. Her benefit at 66 will be calculated from her reported earnings. Her reported earnings are $0.00.
$0.00 a month. Indexed to nothing. Payable never.
She has asked me twice whether the hours count for anything. Both times I have told her that the hours count.
Now let me bring you the article that started this, because you should see the frame before I show you what sits inside it. Rachel Greszler writes in National Review this week that the 3.6% cost-of-living adjustment announced for 2027 — $73 more a month, $880 more a year, an average benefit of $25,300 — is on its way to becoming a cost-of-insolvency adjustment, because the retirement trust fund runs dry in the fourth quarter of 2032, after which incoming revenue covers 78% of scheduled benefits and every check in America is cut 22%. Read her here. She is writing to the young worker who gets handed the bill in 2032. I will tell you what her piece doesn’t have room to print. By the time the cut arrives, I intend to have as few of those young workers on my payroll as the law permits.
That is not a plan. It is a completed project.
Let me show you the completed project’s floor.
One rung down from Darlene is Marisol — Darlene with the building taken off her and the rate raised $1.55 to compensate. Marisol works the home-care route out of a staffing company I own 4 miles from the Zanesville building. She is paid $19.40 a visit. A visit is 90 minutes on the schedule and 70 minutes in the house, and she drives between them on her own tires. She is 61. She has worked that route for 9 years. In 2037 she turns 66, and the check she has been promised her whole life will arrive, and it will be the same figure as Darlene’s.
Three hundred and forty aides are on that company’s roster. At an average of $34,000 in annual billings each, the payroll tax I decline to generate comes to $4,216 per aide.
$1,433,440.
That is a program I did not build, administered by a government I do not serve, and the only part of it I can honestly be asked about is what it cost me to stand outside it: $2,200 for a letter from a lawyer, a payroll registration I never filed, and a binder I keep in the front office where the families can see it. The binder is for the state surveyor. The letter is for me. The rest is a number I review on the first Monday of every quarter, and I will not insult you by describing my feelings about it.
Widen the frame with me.
The trust fund is not a fund. It is a claim — a stack of receipts for money already spent, redeemable only against the wages of people who had not been born when it was spent. Somebody was going to pay for your mother’s room in 2032. The question in 1935 was never whether. It was who, and how much of them. Solomon filed the answer 3,000 years before the first deduction was ever taken out of a pay envelope:
The rich ruleth over the poor, and the borrower is servant to the lender. — Proverbs 22:7
Get this part right, because it is where my students always go astray. I am not the lender. I am the clerk. I am the man who removes the collateral from the shelf the week before the lender comes to count it.
And I am not unusual. I am a curriculum. Chapter 9 of Calibrated Deprivation is titled “Classification.” I wrote it in 1998 and it is in its fourth printing, and the woman who runs the staffing network that supplies my Columbus buildings took my seminar in 2011 and underprices my per-visit rate by 40 cents, and I have told her twice that she is doing it correctly. The class graduates every May into a profession that needs me to explain anything only once.
Now come back down to the floor with me, because 2032 has a face on it.
The trust fund runs dry in the fourth quarter. The average retiree loses $450 a month. My residents lose $450 a month — the Zanesville building is 61% private pay, I have raised the private-pay rate effective 2029, and the families will sign it because the alternative is the county home and the county home has a waiting list I have read. The families will sell something. I have not asked what. That is not my department. My department is staffing, and my staffing is 340 aides cheaper than the state average, and my occupancy is 94%.
Here is where it turns.
Those families will need more money than the check provides. And when they do, some of them will sit in a chair across from a man who sells annuities.
Mira is 68, widowed, sitting in the Tuesday seminar I run out of a strip-mall office in Largo, Florida. Her knees lock when she stands. The coffee I serve her costs me $0.14 a cup. The annuity contract I am going to sign her to tonight will keep her cheaper than the coffee. Her husband is dead and his name is no longer spoken in this office. God bless the actuarial table. It is the kindest thing the federal government has ever done for me.
Here is the arithmetic the lesson was building toward. The COLA on her lap is 3.6%. The mandated haircut when the trust fund runs dry is 22%, rising to 38% by 2100. The payroll tax the trust fund actually requires to sustain the full benefit: 17.3%, up from the current 12.4%. For a median worker earning $65,000, the additional tax the trustees say is needed to keep Mira’s promise whole: $3,200 a year. The fee I charge to administer the rollover into my annuity product when that worker can no longer afford the additional tax: 1.4% of assets, annually, in arrears, for the rest of her life. The federal government is the reinsurer. I am the carrier. She is the policy.
Greszler recommends that Congress give workers the option, within Social Security, to build personal retirement savings they own and can pass on to their heirs. She calls it a reform. I call it my pipeline. I have been waiting for it.
Tonya is a coordinator on the floor of the third-party administrator I own outside Indianapolis. She is 41. Tonya is Mira with a longer horizon and a younger back. The 4% match her employer offers is paid into a target-date fund I sub-advise. The expense ratio is 0.84%. The benchmark is identical to the index fund in her 401(k) menu that costs 0.04%. She is paid in the spread. The personal retirement account Greszler proposes, were Congress to pass it, would be the spread at ten times the volume. The arithmetic is the arithmetic.
I have spent 30 years grading men into the arithmetic by which a 67-year-old’s grocery budget is converted into a 1.4% annual fee stream. My graduates sit on the boards of the firms that pick your 401(k) menu. One of them picked yours. The best of them run the subtraction faster than I do, and I say so with pride. The class will graduate another cohort in May. The cohort is thirty-two. Their average target is a 67-year-old with a $25,300 printout and a 78% trust-fund ratio. I have not priced the next cohort’s curriculum guide. I expect my successor will. He will be cheaper than I am, in the way a cheaper cohort always is. The annuities he writes will be smaller. The fees will be the same.
I am told the longevity curve for 68-year-old women in Florida has terms I have not modeled. I have not modeled them. The printout on Mira’s lap will be paid for the length of time she is alive. I have priced the annuity on the median length of time she is alive. The desk is clean.
Both thy bondmen, and thy bondmaids, which thou shalt have, shall be of the heathen that are round about you; of them shall ye buy bondmen and bondmaids. Moreover of the children of the strangers that do sojourn among you, of them shall ye buy, and of their families that are with you, which they begat in your land: and they shall be your possession. And ye shall take them as an inheritance for your children after you, to inherit them for a possession; they shall be your bondmen for ever. — Leviticus 25:44–46
The rooms are full. I have no complaint to file.
Sterling A. Varice holds the Hayek-Friedman Chair and serves as Dean of Instruction at Warden University’s College of Business and Economics in Richmond, Virginia. He is the author of three textbooks: Divine Mandates for Labor Utilization, Social Obligations for Profit Maximization, and Calibrated Deprivation: A Manager’s Guide to Employee Motivation.