Congress is handing households the bill for a fiscal path it refuses to own.
The U.S. economy is not cooling. Yesterday’s flash purchasing-managers survey, a quick measure of business activity, showed expansion at the fastest pace in five years. Bond markets responded before the Federal Reserve had to.
The 10-year Treasury yield rose above 5% in its biggest one-day move since Donald Trump’s “Liberation Day” tariff announcement almost 18 months ago. The five-year yield also crossed 5% for the first time since 2007. A weak auction of five-year Treasury debt added to the pressure by showing limited demand at the prevailing price.
Here are the numbers behind the repricing. Unemployment stood at 4.1%. Growth was running above trend. Manufacturing hiring reached its strongest reading since February 2021, and new orders grew at their fastest pace since April 2022. Investment in artificial intelligence and resilient consumer spending outweighed energy-price concerns in the survey.
Supplier delivery times stretched, while input costs remained elevated because of high energy prices and supply-chain pressure. That is evidence of simultaneous expansion and cost pressure. It is not, by itself, proof that demand was outrunning productive capacity. The distinction matters. A survey can show inflation pressure without establishing its precise cause.
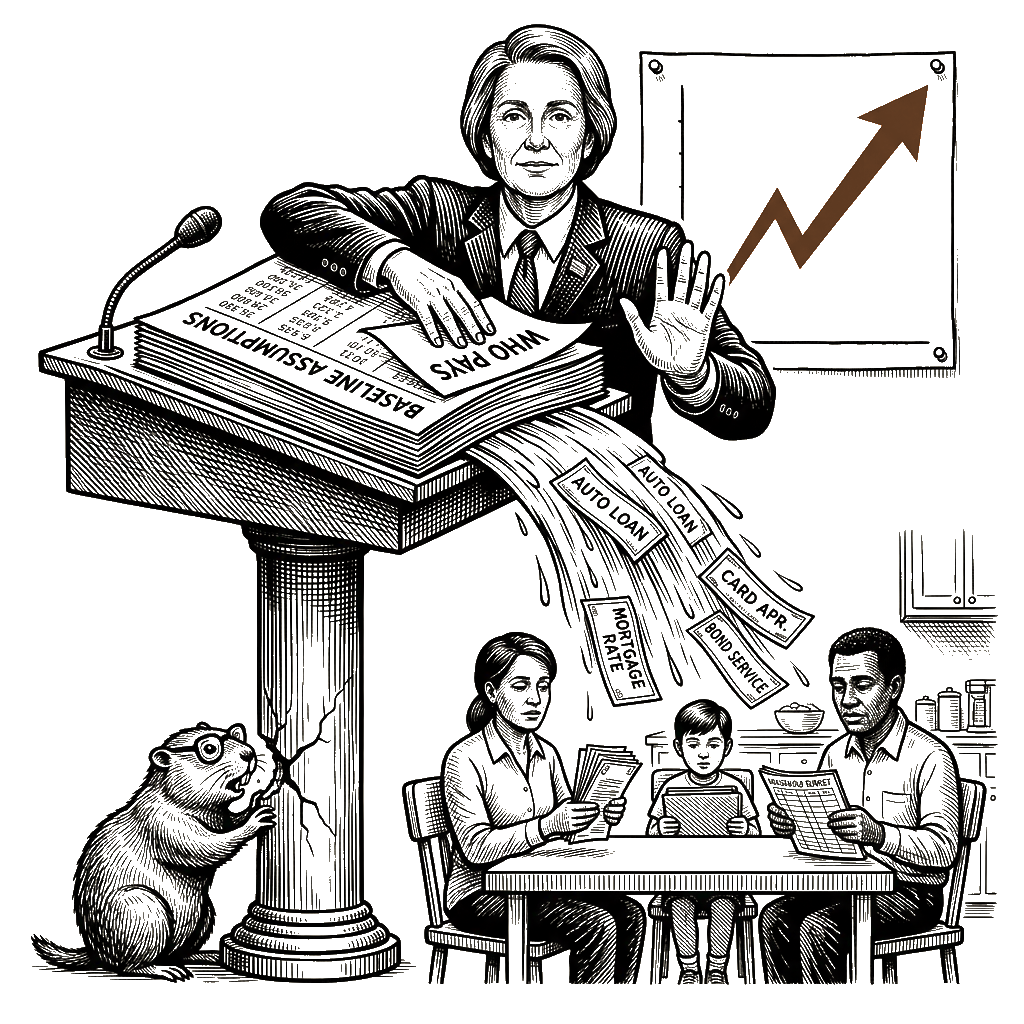
The public consequence is less ambiguous. Higher Treasury yields feed into mortgage rates, business credit, auto loans, and the cost of financing for state and local governments. As interest costs rise, more federal revenue is committed to servicing past borrowing rather than financing current priorities. The budget loses room before Congress formally votes to spend another dollar.
That is the fiscal mechanism. The bond market does not pass a budget resolution. It changes the price at which the government must finance one.
The effect is global because U.S. Treasury debt serves as the benchmark for financial markets. Japan’s benchmark yields reached their highest level in decades. The movement was not confined to American securities; it was a repricing of the reference rate used across the system.
The Federal Reserve’s primary instrument is the policy interest rate, and that instrument is blunt. Its legal assignment is a dual mandate: maximum employment and price stability. Strong activity supports employment. Persistent price pressure argues for tighter policy. The same rate increase can restrain inflation while raising borrowing costs for households and firms.
Ipek Ozkardeskaya of Swissquote described the combination accurately: activity was expanding strongly while price pressures remained elevated. That combination strengthens expectations of further rate increases. The quotation is market commentary, not a forecast. The survey itself cannot determine the Federal Reserve’s decision.
Nor can the bond market determine the distribution of the cost. A higher rate path reaches households through refinancing and new credit. It reaches businesses through working-capital costs. It reaches governments through debt service. The people who absorb those costs did not choose the assumptions embedded in the budget baseline or the financing schedule.
The relevant question is therefore not where yields move next. It is who pays when fiscal choices produce higher financing costs and monetary policy is asked to contain the result. The bond market has stopped pretending that the bill belongs to someone else.