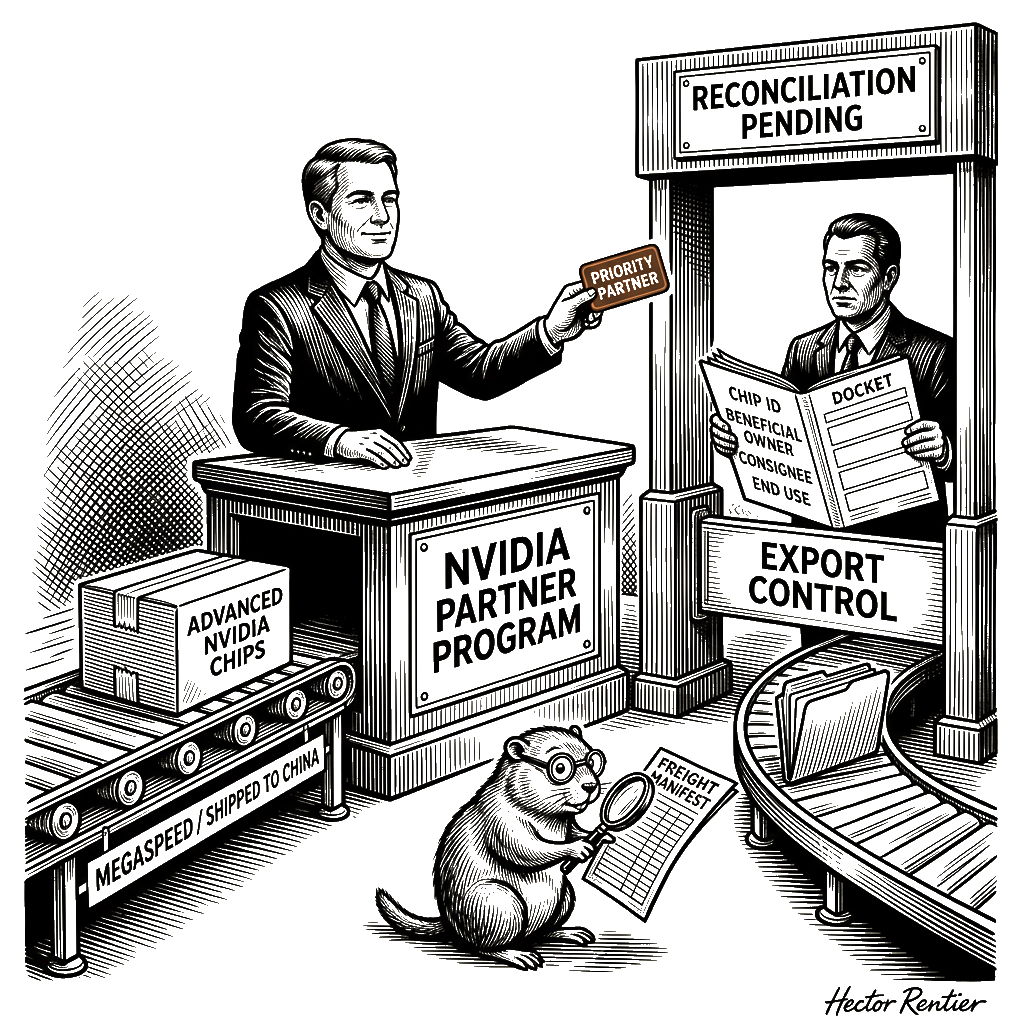
Megaspeed held Nvidia priority while its chips reached China. The Wall Street Journal reported that at least some Nvidia chips obtained by Megaspeed were shipped to China and that Alice Huang cultivated a romantic relationship with Jensen Huang, then Nvidia’s chief executive, in an effort to secure advanced-computing chips for Megaspeed. Kang Wei, the businessman who introduced Jensen Huang to Alice Huang, had known Huang from their videogame-industry days and told people who knew the couple that he had introduced them. They were photographed together at a Singapore restaurant in late 2023 and at Taipei’s Computex conference the following year. The Journal characterised their work as two tracks aimed at the same goal: advancing China’s artificial-intelligence capabilities ahead of those of the United States.
The public record also separates four facts from four gaps. A romantic relationship was cultivated. Megaspeed received an Nvidia cloud-partner designation and priority access. At least some Nvidia chips it obtained reached China. United States authorities are investigating whether export controls were violated. The gaps are equally material: no public record establishes that Beijing directed Megaspeed’s procurement, that the shipped chips reached data centres linked to Kang Wei, that Jensen Huang changed an allocation decision, or that the particular units shipped were the units covered by the restriction at issue. The Journal also reported that Huang has resigned from Nvidia. That fact does not explain the resignation, and it proves no shipment.
It is true that Chinese public records do not establish either state direction or delivery to Kang Wei’s centres. The trouble is that the narrower case does not disappear. The fact that the relationship existed does not establish his intervention in an allocation; the fact that chips shipped does not establish that those chips were prohibited. Those are different propositions, and the investigations exist because the documentary record has not yet joined them.
Export controls cannot make advanced chips disappear. They redirect procurement, raise costs and slow deployment. The dangerous part is not movement. It is divergence between a legal line and a commercial queue. A priority queue is not an export licence. A partner designation is not a border. A relationship is not an allocation record.
By November 2023, Megaspeed had told Nvidia that Alibaba would be an anchor customer and had received designation as an Nvidia cloud partner, with the priority access that designation reportedly conferred. Alice Huang’s registered directorship ended that month amid an ownership restructuring. The designation is not a technological talisman. It is queue management: when inventory is scarce, priority determines whose order reaches the front of the line. It does not manufacture a processor; it decides which customer receives scarce stock first.
Nvidia controls priority among customers for the units it has available. Export authorities control the legal conditions for sale and shipment. Those are different powers, and a corporate partner programme does not merge them. The Journal’s sourcing places Huang’s relationship and Megaspeed’s procurement in the same story. The public documents do not identify Huang as the person who made any particular allocation decision. The relationship is documented. An allocation intervention is not.
Singapore’s investigation makes the remaining problem more concrete. In February 2025, the country opened an investigation into Megaspeed and key officers over suspected false declarations on server purchases. Authorities later found insufficient evidence of a domestic criminal offence, issued Huang a stern warning and barred her from re-entering Singapore. Those measures did not establish that a declaration was false, and they did not establish an export-control violation. The Singapore inquiry concerned suspected false declarations. Investigations into Megaspeed and six other individuals remained open.
Whatever legal theory the unresolved investigation is testing, it would have to reconcile several different records. The identifiers of the chips and servers in the purchase records would need to be matched against shipping and customs records. The declared purchaser would need to be traced through beneficial ownership—that is, through the people who ultimately own and control the purchaser. The certified end user would need to be checked against the actual destination and installation. And the representations in the end-user attestations would need to agree with the physical trail rather than merely accompany it.
Megaspeed describes itself as a “legitimate and lawful business” and says Huang now has no role in it. Those are the company’s words. The company through which all this ran is not easy to examine from outside: Megaspeed’s listed offices yield few traces of an operating business. A corporate description cannot substitute for reconciliation of the records, and a stern warning is not a conviction.
Those records are also not interchangeable. Cloud-partner priority answers one question: who receives a scarce unit first? A chip identifier identifies a particular physical unit. Beneficial ownership identifies who ultimately owns and controls the buyer. Shipment records trace the physical route. End-user attestations record what the buyer certified about destination and use. Remote cloud-access records answer a different question altogether: who used a computing service, and when? They do not necessarily show where any server was located.
A cloud service can be accessed from China without a server crossing a border. A server can cross a border and then be managed remotely from somewhere else. Presence in one place is not proof of presence in the other, and absence from one is not proof of absence from the other. Each record answers a different question. Only their combination can test whether a particular unit lawfully reached a permitted user.
The capital table behind Kang Wei’s data-centre network is more revealing than a founder legend. A late-2021 regulatory filing for Century Longteng listed a 10 per cent stake held by a local Shanghai government body, 27 per cent held by an investment vehicle affiliated with Hexi Capital, Kang’s main business venture, and a controlling 63 per cent held by Shenzhen-listed Century Huatong. Kang later became an executive at Century Longteng. Proposed investments across the network from 2021 through 2024 exceeded $9 billion.
Huatong was known primarily for online gaming, though it had already expanded into data-centre infrastructure. That combination mattered: an operating company experienced in large consumer platforms was joining an infrastructure business requiring capital on an industrial scale, public support and a reliable supply of specialised equipment. The money was not merely financing another building. It was assembling compute capacity across a state-supported network.
In early 2022, Century Longteng signed a framework agreement with Huawei Technologies to collaborate on cloud data centres, energy infrastructure and computing. Washington had already blacklisted Huawei and barred it from access to American technologies. The agreement was not evidence of a particular Nvidia shipment, and it should not be made to do work it cannot do. It does show the kind of computing infrastructure the procurement network was being built to serve.
The Wuhu project made that infrastructure physical. Publicly announced in the summer of 2022, the planned $4.5-billion complex included eight data-centre buildings across nearly 4.1 million square feet—more than seventy football fields—and approximately 24,000 server racks. A rack is the cabinet-scale unit holding processors, memory and the networking equipment connecting them. “24,000 racks” is a more useful measure of intended scale than a promise about the digital future. Wuhu government records showed state support for electricity and infrastructure under Beijing’s “East Data, West Computing” strategy, intended to spread computing capacity across the country. As of April, one building of roughly 500,000 square feet had been registered as completed.
In July 2024, Kang appeared at the groundbreaking of a roughly $5-billion development in Liangshan, a remote area of Sichuan province. Local official accounts identified him as chairman of a Century Longteng-affiliated data-services unit, while corporate filings connected Century Longteng interests to another development in Shenzhen. The portfolio was no longer a loose collection of investments. It included operating centres in a Yangtze River city, a remote western site and the technological heart of the country’s southern coast.
Harold Innis’s staples economy supplies a useful provincial correction. His staples were not merely products; control of their production, financing and movement gave a metropolitan centre leverage over a hinterland. Here the staple is computing capacity: accelerators, software, electricity, finance and the buildings in which the machines operate. Control of the queue that allocates advanced chips matters more than the nominal number of completed facilities. A warehouse full of servers has limited strategic value if the equipment capable of using them cannot be obtained.
My father spent thirty years as a journeyman millwright on the bar mill at Manitoba Rolling Mills. When Gerdau of Porto Alegre bought the mill in 1995, he kept his job while several uncles did not. In the family workshop, his first question was not whether a machine was new; it was whether its owner could open it, diagnose it and put it back to work. The modern version of that question asks who may inspect the declaration, who controls the allocation and who can prove where the chip ended. A machine you may not inspect becomes a machine you must trust. So does a supply chain.
The buildout began before Washington restricted advanced-chip sales to China, so it cannot honestly be described as a response to those restrictions. The trouble is not the sequence. It is that, by the time the procurement channel was being established, the infrastructure programme had acquired a scale and political purpose that made access to advanced accelerators commercially valuable.
Between late 2024 and June 2025, Kang and Alice Huang offered several data-centre projects in Shanghai and Southeast Asia to outside investors. They told prospective investors that they could expect to triple their money in three years and expressed confidence that they had ways to bring Nvidia chips into China. That is the strongest bridge between the procurement channel and the construction programme. It still does not prove that chips reached Kang’s centres or that the Chinese state ordered Megaspeed’s purchases. It establishes that proposed access to chips and data-centre finance were marketed together rather than occurring as unrelated accidents.
The pitch belongs to the corridor Main Street Independent has already traced from Southeast Asia into China. Geography does not make the export-control regime irrelevant; it changes where enforcement must happen. The audit must follow ownership, control, movement and end use rather than stop at the first national border crossed.
Nvidia’s CUDA ecosystem—the libraries, compilers and development tools that let software run on its processors—makes an accelerator purchase the beginning of an engineering relationship rather than an isolated transaction. Code written for one stack must be ported, tested and sometimes redesigned when the supplier changes. Tim Wu’s account in The Curse of Bigness describes the commercial consequence: once a gate owns an indispensable relationship, scale becomes a moat and the buyer’s exit becomes increasingly expensive.
Cory Doctorow’s chokepoint capitalism describes intermediaries positioned to demand concessions from both sides because they control the route. The route here is less picturesque than a marketplace: it runs from accelerator allocation to cloud access, from the software stack to the data centre, and from an investor’s promise of returns to the utility bill at the end of the cable. A chokepoint’s power does not come from building better things. It comes from owning the gate. Priority allocation can lower one barrier while raising another. The customer receives chips sooner but becomes more dependent on the supplier’s tools, while the supplier becomes less exposed to the customer’s ability to leave.
Follow the benefit, then. Megaspeed received priority access and a partner designation, then offered investors data-centre projects coupled with claims of access to Nvidia hardware. Nvidia supplied the scarce units and the commercial status attached to them. Outside investors were offered a tripling of their money in three years. The Chinese state-backed network received capital, electricity, infrastructure and a national policy destination for the resulting capacity.
The public record does not permit a clean dollar-for-dollar calculation linking the procurement and construction systems. Nor has it established a violation. What it does establish is the coupling: commercial priority, access to advanced chips and data-centre finance were presented as one investment proposition.
When one private firm holds both an indispensable product and discretion over priority among buyers, its permission function begins to resemble foreign policy—except that the sales team, not an electorate, answers for it. Nothing in the public record requires us to assume that Jensen Huang intervened. The governance problem survives without that assumption. A regulatory architecture that depends on a private queue remaining uncorrupted, undisclosed and free of unrecorded conflicts is not a control system; it is a promise.
The remedy need not be one ceremonial export announcement. Commerce should require a regulator-readable, near-real-time ledger for advanced chips subject to export controls: allocation priority, chip identifiers, beneficial ownership and control, shipper and consignee, shipment records, end-user attestations and evidence of installation or remote cloud access where relevant. Exceptions should not be granted where the chain cannot be reconciled. Nvidia should disclose the criteria governing partner priority and its conflict-control procedures; Singapore should publish the disposition of the unresolved investigation; and Chinese securities filings should identify state-linked investors and data-centre operators plainly enough for outsiders to test the network.
State direction, delivery to Kang Wei’s centres, intervention by Jensen Huang and the legal status of the particular units shipped remain unanswered. The ledger is still under review. The shipments have already happened.