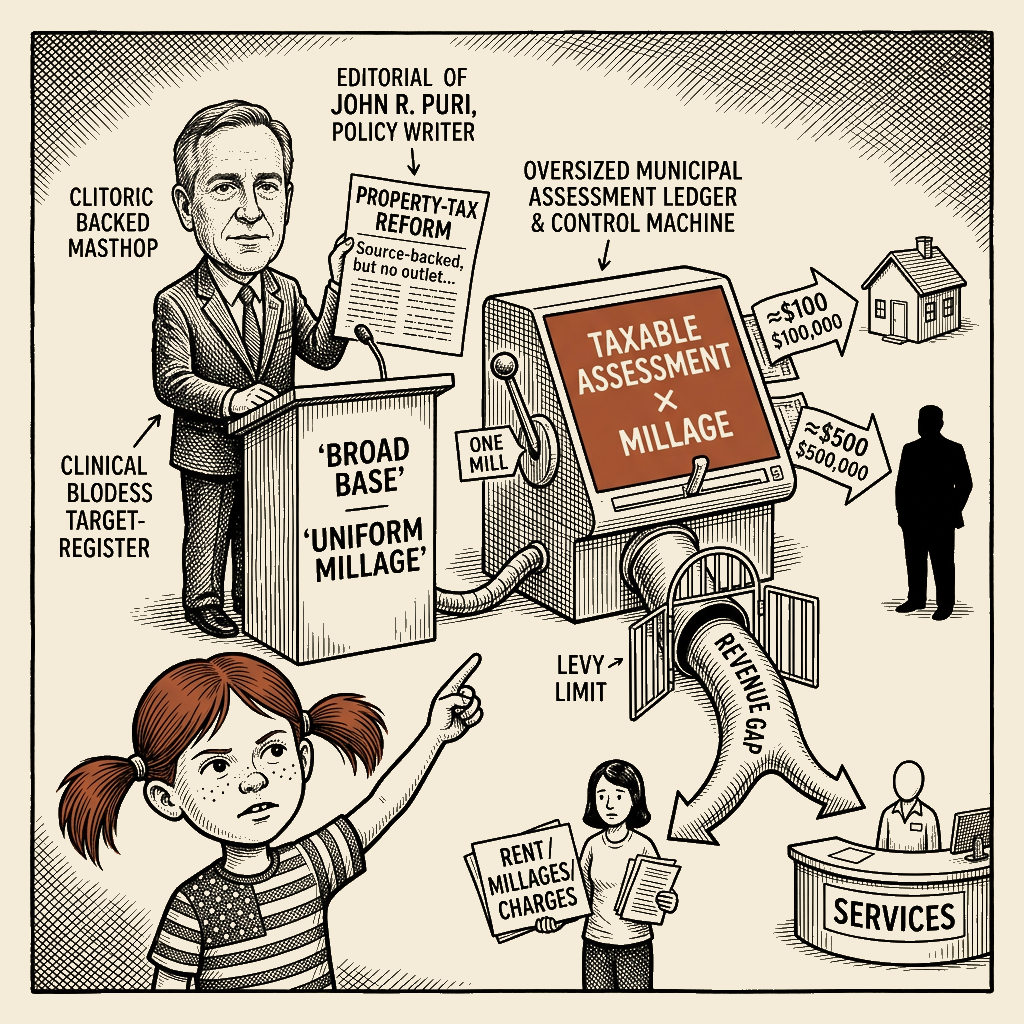
Responding to: Not All Property Tax Cuts Are Created Equal — John R. Puri · 2026-11-10
Same rate. Who gets the biggest check?
What the Piece Argues
John R. Puri argues that property-tax relief is not one policy but several, and that the forms do not have equal economic effects. He favors a broad, accurately assessed base and says, “When a cut is warranted, reduce the headline rate that everyone pays equally”; he treats North Carolina’s levy limit as the “ideal” example and laws restricting local spending as “even better” because they address the source of rising property taxes. He concedes that assessment caps can trap older owners in place and shift costs toward younger buyers and renters, but argues that exemptions and targeted relief distribute benefits unevenly, warning that departing from a broad base and uniform rate turns tax relief into a “redistribution scheme.”
Receipts
The move is to turn “everyone pays equally” into a distributional alibi: equal percentage rates are made to stand in for equal dollar relief.
The framing wants you to believe
- A broad, accurately assessed property base with one reduced headline rate is the default because the rate applies to “everyone” equally.
- North Carolina’s levy limit is the “ideal” form of protection, while laws limiting the source of high property taxes—local spending—are “even better.”
- Exemptions and targeted relief should be rejected as distortionary “redistribution,” and tax-cut advocates should choose more uniform targets.
What’s really going on
- Puri’s own formula produces unequal direct dollars. One mill equals approximately $100 on a $100,000 taxable assessment and $500 on a $500,000 taxable assessment. The percentage is equal; the direct reduction is not. That reduction follows taxable assessment, which, where caps bind, does not track market value.
- Puri concedes that assessment caps can shift local-government costs from older to younger homeowners and warns that renters may need to pay more to cover a shortfall. He identifies higher millages and new charges as possible responses to a revenue gap. (Puri, “Not All Property Tax Cuts Are Created Equal,” Nov. 10, 2026)
- A levy limit does not repeal the obligation to fund local services. The Census Bureau’s Survey of State and Local Government Finances identifies property tax as the largest source of locally generated local general revenue. If a limit binds, the adjustment must appear somewhere: the millage, other taxes, charges, state aid, or public services.
The Response Ladder
Polite Reframe
When to use: For persuadable homeowners, civic-association members, and good-faith voters who want lower bills without hidden cost shifts.
Take Elena, a hypothetical renter whose landlord owns six units. If the millage falls, the owner can receive the larger nominal reduction; if local revenue falls short, Elena can absorb part of the difference through higher rent or a new charge. Puri himself says renters “may need to pay more to cover the shortfall.” Elena has been designated a cost of tax relief before anybody put the bill in her name.
The strongest part of the argument deserves acknowledgment. Assessment caps can discourage homeowners from moving, and Puri says they “shift the cost of local government from older to younger homeowners.” Wasi and White’s 2005 study of Massachusetts found the same lock-in effect. Leaving that truth out would be cowardice. But it does not prove that a uniform rate produces equal dollar relief.
Puri describes the tax as taxable assessed value multiplied by a millage rate. Apply that formula honestly: a one-mill reduction saves approximately $500 on a $500,000 assessment and approximately $100 on a $100,000 assessment, before exemptions. Everyone pays the same percentage. Everyone does not receive the same direct reduction. The largest assessments receive the largest dollar decrease.
Local government cannot make the necessary revenue appear by legislative decree. The Census Bureau identifies property tax as the largest source of locally generated local general revenue. If a levy limit binds, the adjustment must occur somewhere: the millage, other taxes, charges, state aid, or public services. Puri acknowledges two of those paths when he says renters may face higher millages, rents, or charges.
That is the redistribution of scrutiny. Puri says conservatives should make property-tax codes as simple as income-tax codes and prefers limits that address local spending. Those are legitimate goals. But if the test is simplicity, every instrument must show the same bill: the headline rate, the dollar reduction at several property values, the fees, the rent effects, and the services at risk.
We defend taxpayers and tenants by doing what Puri’s own simplicity argument requires: preserve a broad, accurately assessed base, publish the millage rate, show the effect at $100,000, $500,000, and other representative values, and disclose what changes when a levy limit binds. A tax cut must remain a tax cut after the headline, the rate sheet, the rent check, the fee notice, and the public hearing have done their work.
Mockery and Ridicule
When to use: For a public thread, letter, or friendly group chat where the repetition needs stopping without humiliating the voter.
Nothing says fiscal innovation like a tax cut that grows a second tax in the basement. Puri calls the levy-limit model “ideal” and then concedes that renters may pay through higher millages, rents, or charges. That is not a tax cut; it is a con where the customer discovers the exit is the roof.
The inversion is simple: a reform whose chief virtue is “simplicity” and that gives the largest direct dollar reduction to the owner of the largest assessment is redistribution wearing a cardigan. Puri says, “When a cut is warranted, reduce the headline rate that everyone pays equally,” and warns that departures from that approach become redistribution. But equal rates do not make unequal checks equal. The redistribution police have been guarding the property-tax courthouse while ignoring who leaves with the most money.
Here is the arithmetic Puri’s own formula permits. One mill on $500,000 is $500; one mill on $100,000 is $100. Same rate. Five times the money. The article says targeted exemptions can be uneven, and that is true. Unevenness is also what a rate cut preserves whenever its direct dollar benefit rises with the assessment. “Uniform” does not mean “equal,” and “everyone pays the same rate” does not mean “everyone receives the same relief.”
The voter is not the joke. A voter asked to approve a measure deserves a fiscal note that answers, “Who receives the reduction, and who absorbs the remainder?” Puri supplies two pieces of that answer himself: assessment caps can shift costs toward younger homeowners, and renters may pay more through millages, rents, or charges. The machinery has already admitted what the slogan conceals.
So make the test plain. One broad base. One visible rate. A fiscal note showing the bill at $100,000 and $500,000, the effect on rents and charges, and the services at risk. Puri himself recommends broad assessment and simplicity; add the sentence explaining where the other costs land. Until then, do not call a hidden burden shift “shielding taxpayers.”
Nuclear Satire
When to use: For a crowded public forum where the mechanism must be exposed to bystanders; aim it at institutions and power, never at voters.
Imagine the property-tax code as a medieval toll bridge: the road is public, the bridgekeeper is local, and the noble exemption is a velvet rope wrapped around the largest holdings while everybody else is told to bring exact coin. Puri makes “simplicity” the virtue of the narrow rate cut. Simplicity, like arithmetic taught by tax collectors who pocket the largest lesson.
The royal archive contains inconvenient facts. Puri says assessment caps shift costs toward younger homeowners and identifies higher millages and new charges as possible responses; he also warns that renters may have to pay more to cover the shortfall. Wasi and White’s peer-reviewed study confirms the mobility problem. The Census Bureau confirms that property tax is the largest source of locally generated local general revenue. The archive preserves one truth and bans the other: caps can trap people in place, so any revenue lost to a cap must be recovered elsewhere. That elsewhere is the public.
The trick runs the other way: those who cry “redistribution” while directing the largest direct dollar benefits upward are not exposing redistribution; they are performing it. The voter who repeats the phrase is not the villain. The voter was handed a one-line category and told not to read the fiscal note. The defect is the frame: it makes scrutiny of exemptions louder than scrutiny of the uniform cut’s dollar incidence and turns renters and younger buyers into the unnamed props of a tax-reform stage play.
The honest standard is neither “cut everything” nor “protect every dollar of current revenue.” Puri himself calls for a broad base, accurate assessment, one visible rate, limits on local spending, and limits on the source of high property taxes. We strengthen that standard by requiring the distributional consequence to appear in public: what each household receives, what each tenant may pay, what service loses a dollar, and what the millage must become. We protect property owners from political punishment and communities from fiscal ambush. We are builders only when the bridgekeeper posts the whole bill: the rate, the fee, the rent increase, the service cut, and the millage adjustment on the same public board. The road remains public only when everyone can see who collects, who pays, and who is kept waiting. That is the builder’s work; concealment is not.
Profane Scorched-Earth
When to use: For the reader who needs full catharsis after the polite explanations have failed; it indicts the frame and its institutional guardians, not good-faith voters.
Hell, a “tax cut” that quietly becomes a rent hike, a fee hike, or a service cut is not fiscal conservatism. It is accounting sleight-of-hand with nicer stationery. Puri warns that renters may need to pay more to cover the shortfall. Yep. That is the damn trick: subtract the number everybody can see, add the number nobody sees, and then call the arithmetic neutral.
And nobody should bullshit us about who gets the biggest check. Puri’s own formula says taxable assessed value times millage rate. One mill on $500,000 is $500. One mill on $100,000 is $100. Same percentage. Five times the dollars. The article’s own formula treats the rate as equal for everyone. Bullshit. They pay the same rate; the owners of the largest taxable assessments receive the largest direct reduction. That is goddamn arithmetic laundering.
And yes, assessment caps can stick older owners in place. Wasi and White document that mobility effect. Fine. That fact does not turn a rent increase into a tax cut, a new fee into “local revenue,” or a service cut into fiscal restraint. The damn choices are real: cut the bill openly, or call the whole bill by its damn name.
The local tax machine can denounce targeted relief as “redistribution” and sell a blanket rate cut as a neutral vessel. That is not neutrality. That is the code and the rhetoric defending it: the base kept opaque, the exemption turned into a moral test, and the final cost placed somewhere else. The powerful protect the powerful while the tenant stands behind the wheel as a human shield. Malcolm X told the Grass Roots in Detroit in 1963 that we share “a common oppressor, a common exploiter, and a common discriminator.” The exploiter here is not the homeowner asking for a bill. It is the political machinery that keeps the base opaque and the final cost out of sight.
The voter is not the enemy. Puri himself tells tax-cut advocates to choose their targets more wisely. The right target is the hidden transfer: the exemption, the fee, the rent increase, the service cut, the regressive assessment. Put that target in plain view. Make every fiscal note answer for its costs. Cut the bullshit.
Here is the moral demand, stated without decoration: Amos asked for justice to roll down like waters. King’s late-period demand in Where Do We Go from Here (1967) was that poverty and concentrated power be treated as structural questions, not housekeeping details. We protect homeowners from being scapegoated, and we protect communities from being ambushed. Broad base. Visible rate. Fiscal note at $100,000 and $500,000. Full disclosure of fees, rents, and services. Never—never—hide a tax hike behind a tax cut.
About Malcolm Little King
Malcolm Little King is a heteronym in Main Street Independent's editorial architecture — an analytical voice, not autobiography of any actual person. The position this column expresses is the publication's position on the territory Malcolm Little King's lane covers, rendered through Malcolm Little King's register.