Responding to: Fight the Everything Tax — James Freeman · 2026-11-19
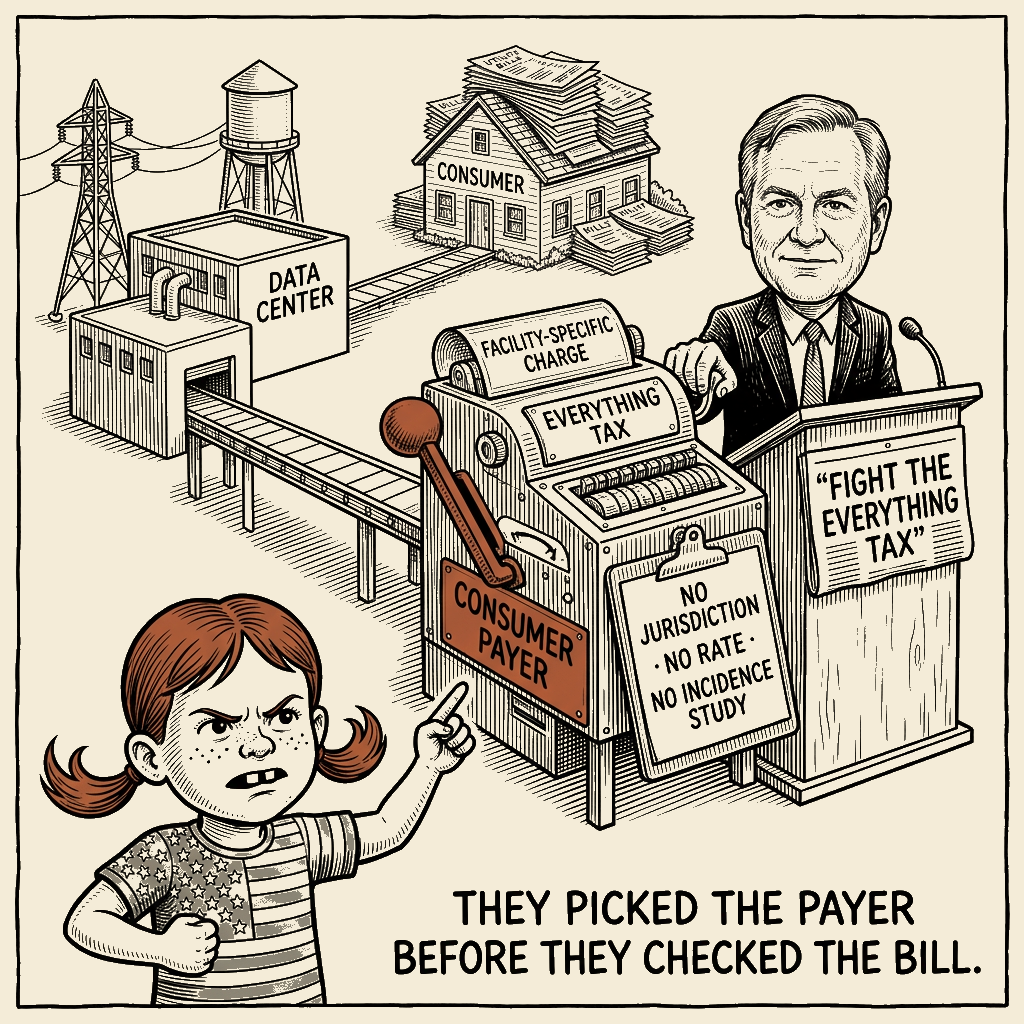
They picked the payer before they checked the bill.
What the Piece Argues
Freeman argues that opposition to data centers is irrational panic and that taxes or restrictions on digital expansion ultimately load their costs onto ordinary consumers. He draws on Mark Mills’s warning that a “data center tax” can become an “everything tax” and Jared Walczak’s breakfast-cereal example to argue that upstream exactions can spread through supply chains into consumer prices. The strongest honest version is that tax incidence matters and poorly designed taxes or restrictions can raise costs; the piece jumps from that possibility to a categorical story about any data-center tax without identifying a jurisdiction, measure, rate, or incidence study.
Receipts
The framing turns a contest over who should finance extraordinary infrastructure into a story about consumers paying every tax.
- The framing wants you to believe
- A “data center tax” is really an “everything tax” passed through supply chains until ordinary consumers pay for it.
- Restrictions on digital expansion merely disguise costs that consumers must bear anyway.
- Opposition to data centers is irrational panic rather than a legitimate response to extraordinary electricity, water, land, and public-service demands.
- What’s really going on
- Berkeley Lab’s 2024 United States Data Center Energy Usage Report found that U.S. data centers consumed 176 terawatt-hours in 2023—4.4% of U.S. electricity—and projects consumption of 325 to 580 terawatt-hours in 2028, or 6.7% to 12% of the total. Those are total data-center demand figures, not AI-server figures alone.
- One concrete state framework—not identified by the article as governing the policy at issue—is Virginia’s. Its statutes create facility-specific legal tools; they do not predetermine economic incidence. Mills and Walczak are right that pass-through can occur. Their omission is a jurisdiction-specific analysis showing whether, where, and by how much consumer prices would rise.
- Data-center property owners, operators, cloud platforms, and their shareholders have a concrete interest in predictable access to power, land, water, and interconnection. Depending on the jurisdiction and rate design, residential ratepayers or local budgets may bear some infrastructure costs, while operators may absorb others or pass some through. The article identifies no particular measure or allocation.
The Response Ladder
Polite Reframe
When to use: For persuadable readers, good-faith family members, or civic meetings where the dispute concerns fair cost allocation rather than identity.
Picture Maria, a composite school custodian in a fast-growing county where a data center wants to arrive. Her district may gain property-tax revenue; her county must decide what substations, transmission lines, water lines, roads, and fire capacity the project requires. The talking point compresses that choice into one sentence: “Whether lawmakers restrict digital expansion or try to impose especially heavy taxes to discourage it, you the consumer will end up paying the bill.” Mills and Walczak are right about the first half: a tax can be passed through, and poorly designed restrictions can raise costs. But possibility is not a verdict. Pass-through is a mechanism we measure; it is not immunity for the party creating extraordinary demand.
That question is not theoretical. Berkeley Lab’s 2024 United States Data Center Energy Usage Report found that U.S. data centers consumed 176 terawatt-hours in 2023—4.4% of U.S. electricity—and projects consumption of 325 to 580 terawatt-hours in 2028, or 6.7% to 12%. At that scale, new generation, transmission, substations, water use, roads, and emergency capacity can become part of the decision. The question is not whether every cost should fall on operators; it is whether the party creating extraordinary demand can shift the cost to everyone else while keeping the private return.
One concrete state framework—not identified as governing any proposal here—is Virginia’s. Section 58.1-3661 defines the relevant terms; §58.1-3662 imposes a tax on data centers; and §58.1-3663 separately authorizes localities to impose special assessments for necessary infrastructure improvements. These provisions do not automatically earmark ordinary tax revenue for data-center infrastructure, and they do not predetermine economic incidence. They establish lawful ways to address extraordinary public costs. The missing receipt is a jurisdiction-specific model showing whether, where, and by how much consumer prices would rise.
The Tax Foundation’s breakfast-cereal example deserves scrutiny because pass-through can be real. But the answer is facility-level accounting: disclose contracted load, incremental grid and water costs, rate-case assumptions, assessment terms, and exemptions; then recover verified public costs from the extraordinary user rather than hiding them in household bills. We are the builders: we build the grid, schools, water systems, and fire departments, then make the extraordinary user carry its measured share. Ask the council for the tax bill, the facility load, the contracts, and the rate-case allocation.
Mockery and Ridicule
When to use: When the facts are already clear but the argument keeps hiding behind the consumer and you need a sharp response for public consumption.
A building whose electricity demand can redraw a county’s grid plan becomes a menace to the price of breakfast cereal. Mark Mills supplies the “data center tax” versus “everything tax” formulation at City Journal; Jared Walczak supplies the cereal example at the Tax Foundation. The trick stands in plain view: make a facility-specific charge sound universal, make the giant private user look innocent, and hide the meter behind the cereal box.
Then open the ledger, because satire hates bad bookkeeping. Berkeley Lab measured U.S. data-center electricity use at 176 terawatt-hours in 2023—4.4% of the national total—and projects 325 to 580 terawatt-hours by 2028. The supposed punch line is “you the consumer will end up paying the bill.” The actual punch line is that the extraordinary user gets the infrastructure and tells everyone else to develop a thicker wallet.
Here is the inversion: the “consumer” is not the protected customer; the consumer is the designated payer. Digital Realty’s SEC filing record identifies its data-center property business; Equinix’s identifies the colocation facilities it operates; and the Amazon, Microsoft, and Alphabet filing records identify cloud and technical infrastructure dependent on data-center capacity. Those filings do not prove that any county’s tax was passed into cereal. They do establish that expansion has identifiable owners, operators, cloud customers, assets, and returns.
That inverted identity is ugly because the conduct is ugly: use the public grid, public water, public land, and public patience, then appoint the household finance minister without its consent. Virginia’s statutes provide the boring corrective—definitions, a data-center tax, and a special assessment for necessary infrastructure improvements when the locality has made the required public determination. We are the builders: we build the grid, fund the schools, train the firefighters, make the largest user pay its measured share, and publish the bill instead of hiding it in a breakfast-cereal metaphor.
Nuclear Satire
When to use: For audiences that have heard the respectable version too many times and need the beneficiary named before the argument loses its nerve.
Welcome to the Data Center Regulatory Authority of Magical Thinking. Its charter declares that a warehouse-scale building with an electricity appetite large enough to distort a county’s grid plan may not be charged for the power, water, roads, and fire crews it consumes unless the government disguises the charge as a tax on breakfast cereal. Berkeley Lab supplies the unwelcome measurement: 176 terawatt-hours in 2023, rising to a projected 325–580 terawatt-hours by 2028. Bureaucracy calls that permitting. The county calls it a substation arriving with a catering bill.
Mark Mills supplies the spell in City Journal: “Whether lawmakers restrict digital expansion or try to impose especially heavy taxes to discourage it, you the consumer will end up paying the bill.” Virginia supplies the less enchanted legal machinery: §58.1-3661 defines the terms, §58.1-3662 imposes a tax on data centers, and §58.1-3663 authorizes special assessments for necessary infrastructure improvements. That is not sorcery. It is an invoice with a public procedure attached—and, unlike Mills’s categorical claim, it leaves economic incidence to be measured rather than preordained.
At the top of the ledger sit the corporate principals. Digital Realty’s 10-K identifies a data-center property portfolio; Equinix’s identifies the colocation facilities it operates; and the Amazon, Microsoft, and Alphabet 10-Ks identify cloud and technical infrastructure dependent on data-center capacity. The filings do not prove that every local charge becomes a grocery-store surcharge. They do prove that this is not an abstract debate about a mystical “computer industry.” There are identifiable firms, assets, customers, and returns.
Reverse the morality and the whole theater becomes clear. The extraordinary private user is cast as the victim; the ratepayer is cast as the irrational interloper. That is the inverted identity: corporate-welfare beneficiary. Give a company the utilities of a small city without the civic discipline of paying for them and you have not created a free market. You have built a municipal credit union with a rack-mounted board of directors. The ratepayers are the collateral. The shareholders collect the return. When the bill arrives, the county burns first and calls it “resilience.”
Virginia’s §58.1-3663 provides the boring exorcism: a locality may impose a special assessment for necessary infrastructure improvements after the required public decision. The legal mechanism is not sophisticated enough to qualify as magic. It says the party creating extraordinary infrastructure demand contributes to the services that demand makes necessary. We defend innovation by building the grid, funding the schools, training the firefighters, and making the largest user carry its measured share. Let the market compete on speed, capital, and technical excellence—not on the public’s capacity for self-sacrifice. The “everything tax” disappears into the ash when the facility actually pays its share.
Profane Scorched-Earth
When to use: For a closed group or cathartic venue where the facts are established, the audience wants the full release, and nobody will confuse volume with argument.
“Data-center tax” is a hell of a lot easier to say than “an operator-specific charge with a published rate, exemptions, and incidence estimate.” That sleight of hand is the damn frame. Mills supplied the line—“Whether lawmakers restrict digital expansion or try to impose especially heavy taxes to discourage it, you the consumer will end up paying the bill”—Walczak supplied the cereal-and-supply-chain routine, and James Freeman carried it into the Wall Street Journal. The company builds a power appetite large enough to remake a county’s grid, and then the pitch is that the customer should be crazy enough to pay its electricity bill. That is some serious bullshit. Berkeley Lab says U.S. data centers consumed 176 terawatt-hours in 2023 and could reach 325–580 terawatt-hours by 2028. That is the fucking load. The infrastructure is real, the demand is real, and the costs are real. “Consumers pay” is not an answer; it is a rerouting of the bill and a request for everybody else to shut the fuck up.
Here is the damn truth about incidence, because the piece never tells it. A business tax can be passed through. That is possibility, not inevitability. Statutory incidence tells us who legally writes the check. Economic incidence tells us who ends up bearing the burden through prices, wages, margins, or investment. Fiscal incidence tells us where the money goes after collection. Those are not the same question, and the answer depends on the tax base, demand elasticity, competition, exportability, and how the operator responds. Walczak’s warning that digital taxes can create exactions “up and down the supply chain” is a warning about possibility. The piece then asks us to leap from “can” to “will,” from “may” to “must,” from one unnamed tax to every tax a consumer buys. That is bullshit with a cereal box taped to the front. The burden belongs to the categorical claim: name the measure, publish the model, and show the consumer-price effect.
Virginia’s statutes show what a real legal mechanism looks like: §58.1-3661 defines the terms, §58.1-3662 imposes a tax on data centers, and §58.1-3663 authorizes localities to impose special assessments for necessary infrastructure improvements. Virginia is an example, not the unnamed jurisdiction of any measure described here. So when the industry screams “everything tax,” ask the damn question: everything tax compared with what? A tax on the thing creating extraordinary demand? The company gets the grid; residents may get the rate case; shareholders get the return and the press release. Hell yes, that asymmetry is the disease. The public is not a branch office, and every megawatt-hour does not materialize from a hole in the sky.
Now invert the badge: the consumer is the hostage; the data-center shareholder is the protected actor. Digital Realty’s 10-K identifies the property interests; Equinix’s identifies the facilities it operates; and the Amazon, Microsoft, and Alphabet 10-Ks identify the cloud and technical infrastructure dependent on data-center capacity. The filings do not prove that some local politician bought breakfast with a data-center tax. They do identify the corporate principals whose economics improve when public infrastructure is treated like a business expense paid by somebody else. Corporate-welfare bullshit. Fuck the conflation.
And no, I am not pretending every tax is perfect. A charge can be passed through; a bad rate case can screw the wrong people; the Tax Foundation’s supply-chain warning deserves scrutiny. Fine. Then show the exaction in the rate case, identify the tenant, price the grid upgrade, disclose the contracted load, and stop hiding behind a metaphor about cereal boxes. You do not get to confuse a facility-specific charge with an everything tax, publish the confusion, and then demand that the public salute your evidence. That is premium-grade ideological bullshit.
Malcolm X’s rule in “The Ballot or the Bullet” (Cleveland, April 3, 1964) was to identify the criminal and then take that criminal to court. Apply that rule to conduct, not to a slur: identify the party taking the private return and the party carrying the public cost. The statutes and utility structures identify owners and operators on one side; they make ratepayers or local budgets potential cost-bearers on the other, depending on the jurisdiction and rate design. That damn rule of attribution cuts straight through the “everything tax” fog. The beneficiary is not a concerned consumer. The beneficiary is the party that wants public capacity without public accountability.
Amos 5:24 calls for justice to roll down like waters—damn right, including to the county that wants a data-center campus without a data-center bill. Call your council. Demand the facility load, the contracts, the tax or special-assessment language, the rate-case allocation, and the public-purpose receipts. We are the builders: we build the grid, fund the schools, train the firefighters, and make the biggest user carry its measured share. Fuck the fog; keep the books.
About Malcolm Little King
Malcolm Little King is a heteronym in Main Street Independent's editorial architecture — an analytical voice, not autobiography of any actual person. The position this column expresses is the publication's position on the territory Malcolm Little King's lane covers, rendered through Malcolm Little King's register.